

How to read and trade your asset understanding the VIX Expiry
Today is VIX expiration, an event traders on social media have increasingly dubbed “VIXperation.” It is a recurring source of confusion, especially for traders who track volatility products without fully understanding how VIX actually settles.
VIX expiration works very differently from equity or index option expiration. It is tied directly to VIX futures settlement and the pricing of SPX options used in the VIX calculation. Because of that structure, expiration can influence not only volatility products like VIX futures and VIX-linked ETFs and in some cases SPX.
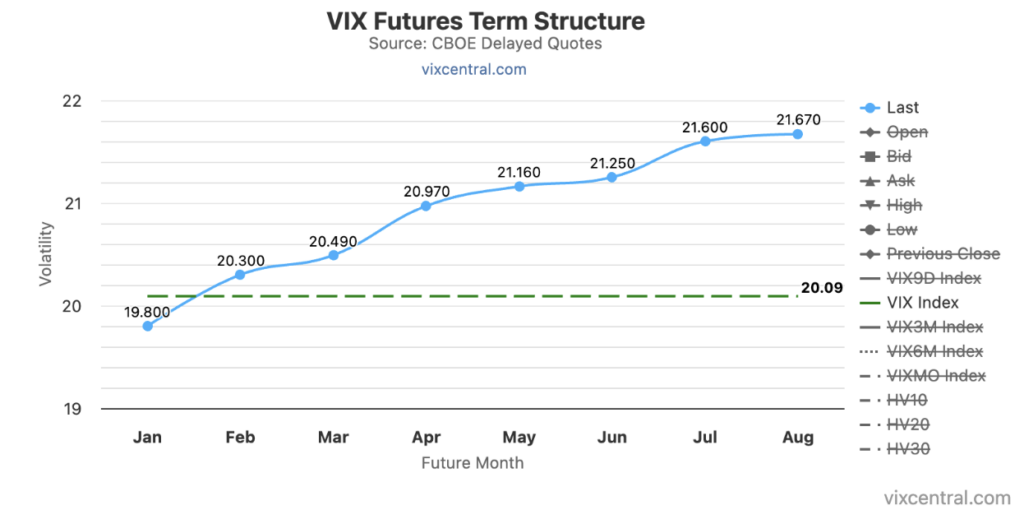
With the VIX term structure currently in contango, understanding how that impacts expiration becomes even more important. Contango plays a central role in how volatility products behave into settlement, how futures prices converge, and why certain volatility strategies tend to perform consistently while others lose money slowly and quietly over time.
This article breaks down what VIXperation actually is, why contango matters specifically at expiration, and what traders should be paying attention to when positioning around it.
What Is VIXperation And Why It Matters
- VIXperation refers to the monthly expiration of VIX futures and VIX options, but it is important to understand what these contracts actually settle to. Unlike most products traders are familiar with, VIX contracts do not settle to the spot VIX index you see quoted throughout the trading day.
- Instead, settlement is based on a special opening calculation known as VRO, sometimes called the Special Opening Quotation. This value is derived from a specific strip of SPX options with defined maturities, not from where spot VIX happens to be trading. That distinction alone explains a large portion of the confusion traders experience around VIX expiration.
- Settlement takes place on Wednesday morning, thirty days before the following month’s SPX options expiration. Once that process is complete, the expiring VIX future effectively disappears and the next month’s contract becomes the new front-month future. VIX options expire on the same day as well and are cash-settled based on that settlement value. Because they are European-style options, they can only be exercised at expiration, not before.
All of this matters because VIX futures are converging toward the settlement value, not toward spot VIX. Traders who assume that spot VIX alone drives profits often struggle to understand why their positions behave unpredictably in the days leading up to VIXperation. Those final sessions can see sharp adjustments as hedges are unwound and futures prices realign with where the market expects the settlement to land.
Contango And The VIX Futures Curve
The VIX futures curve is currently in contango, which means longer-dated VIX futures are trading at higher prices than the near-term contracts. This is the normal state of the volatility market and reflects the broader expectation that volatility tends to revert back toward its long-term average over time.
Contango also tells you something important about market psychology. Even when the VIX has recently spiked, a contangoed curve signals that the market does not believe elevated volatility will persist. In other words, fear is viewed as temporary rather than structural.
Heading into expiration, contango has an additional mechanical implication. Let’s assume Spot, M1 and M2 are all in contango. During expiration, these all roll down the curve. What does that mean? Month 1 becomes Spot and rolls down to become Month 1. So generally that does not create upward pressure on the VIX futures. On the opposite side, each futures contract experiences a downward pressure as it converges to spot.
It is important to separate this from spot VIX behavior. Spot VIX is calculated directly from SPX options (near term OTM Calls Puts) and does not get “pushed higher” by futures rolling. The pressure shows up in volatility products tied to futures, not in the index itself.
Remember:
- SPX options market drive VIX Spot
- VIX Futures do Not feed into the VIX spot formula
This is usually a source of confusion for traders.
VIX Expiration And Roll Decay
VIX roll decay, often referred to as negative roll yield, is a direct consequence of contango in the VIX futures curve. Products that aim to maintain constant-maturity exposure, such as volatility ETFs and ETNs, are forced to sell the expiring, lower-priced futures contract and replace it with a more expensive one further out on the curve.
This process happens incrementally through daily rebalancing, but expiration is when the transition becomes most visible. As the curve fully shifts forward, the cost of maintaining exposure shows up more clearly in price action. Each roll effectively leaves the product owning fewer units of volatility because higher-priced futures require more capital per unit of exposure. Even if volatility itself goes nowhere, value is steadily eroded. Basically they have to sell the cheaper contracts M1, and buy the most expensive M2 futures – remember the curve is in contango sloped upwards.
That structural decay is why long volatility products tend to bleed in calm or range-bound markets and why holding them without a clear timing catalyst is usually a losing proposition. VIXperation tends to highlight this effect as the curve reanchors to the next front-month contract.
Do they have a huge effect, generally these flows are not that big to have an effect based on our research. They are more of a performance lag than market impact.
Learn About the Importance of the VIX.
What Traders Should Watch And Consider
- When the VIX curve stays in contango into expiration, it offers several clues about how volatility and equities are likely to behave around that period.
- Volatility spikes that fail to flip the curve into backwardation tend not to last. Without a sustained increase in fear, elevated implied volatility has a hard time sticking. In those conditions, volatility usually mean-reverts rather than developing into a sustained trend.
- At the same time, short volatility strategies benefit from a built-in structural advantage. Defined-risk volatility selling aligns naturally with roll decay, although timing still matters. Expiration weeks can bring sharp, short-lived moves before volatility compresses again, and being early or poorly positioned can be costly.
- It is also important not to assume that a move higher in volatility means equity downside is finished. A contangoed curve suggests the market has not fully priced in prolonged stress, which leaves room for additional short-term equity weakness. However, it also indicates that fear has not reached a systemic or panic-driven level.
- Most importantly, traders should avoid viewing VIX expiration itself as a directional signal. It is a mechanical process. The edge comes from understanding how futures reposition, how the term structure adjusts, and how volatility products reprice once the roll is complete.
Outlook and Strategy Considerations for Tomorrow’s VIX Expiration
As we head into tomorrow’s VIX expiration on January 21, 2026, the current setup provides a useful real-time example of the mechanics discussed earlier. Spot VIX has recently pushed up toward the 20 area, driven by geopolitical headlines and a broader equity pullback. Despite that move, the futures curve remains in mild contango, though it has flattened noticeably.
Settlement and Immediate Post-Expiration Dynamics
The front-month future has already moved close to spot VIX, which suggests the VRO settlement is likely to land somewhere between 18 and 21, depending on overnight positioning in SPX options. Options pricing implies a relatively contained move, with the expected range centered around roughly 19 to 21 from current levels.
With the curve flat to mildly contangoed, the post-expiration setup points to a modest downward pull on the new front-month February contract as roll mechanics take over. Volatility products tied to futures may see a mechanical pop as the curve reanchors, but that move can fade quickly if spot VIX stabilizes. Realized volatility in the S&P 500 remains low relative to implied levels, and without sustained equity selling pressure, volatility has room to drift back toward the high-teens as the day progresses.
One interesting thing is that all of the SPX levels have not moved including the 1day Min Max, so unless you see a huge overnight move, tomorrow looks stable – for now.

Upside Risk Scenarios
There are still clear upside risks to monitor. Headlines tied to geopolitical developments or trade rhetoric, particularly comments from former President Trump at Davos, could inject fresh uncertainty. A surprise in UK inflation data could also spill over into global rate expectations and push volatility higher intraday.
In those scenarios, VIX could spike into the low-20s, potentially forcing the curve into backwardation and amplifying equity downside. Around the VRO calculation itself, dealer hedging flows may also produce brief bursts of SPX volatility.
Watch the Q-Score for that – it did pick on the recent spike.

Downside Risk Scenarios
On the downside, the calendar is relatively light, which favors mean reversion. In the absence of new catalysts, volatility sellers may step back in once expiration passes, pushing VIX back toward the 17–18 area. Recent volatility spikes have followed a similar pattern, rising on headlines but fading without triggering a sustained curve inversion.
Overall View
The near-term bias for VIX remains neutral to slightly bearish, with a likely settlement around 19–20 and a tendency to fade post-expiration unless new shocks emerge. The flat curve provides some cushion but also reflects underlying fragility. Any move into backwardation would be a meaningful warning signal. Importantly, this expiration should not be viewed as a directional event in itself. It is mechanical, and the edge comes from understanding how futures reposition and how volatility products reprice once the roll is complete.
What to Watch
Key signals include the spread between spot VIX and futures, changes in curve shape, SPX option positioning ahead of the VRO calculation, and headline risk during the European and U.S. sessions. Moves above the low-20s would favor defensive positioning, while a drift back below 18 would reinforce the mean-reversion case.
As always, this is a probabilistic setup, not a forecast. In contango environments, volatility tends to revert more often than it trends, but timing and risk management remain critical.
Conclusion
VIXperation is not about predicting fear, but about understanding structure. When the VIX futures curve remains in contango into expiration, volatility products face built in decay, and elevated volatility is often temporary rather than durable.
Traders who understand how VIX futures settle, how roll decay works, and why contango matters gain an edge over those who trade volatility directionally without context. Tomorrow’s expiration is not a signal by itself, but it is a reminder that volatility is a market of mechanics, not emotion.
Knowing how those mechanics work is what separates informed positioning from costly assumptions.