

Introduction – Gamma Across Expirations
Options markets play a critical role in shaping how modern equity indices behave, and the S&P 500 (SPX) is no exception. Beneath the surface of price charts and macro headlines lies a complex web of positioning driven by options traders and market makers. One of the most useful ways to understand this structure is through Gamma Exposure (GEX) a measure of how dealer hedging activity can influence price movements.
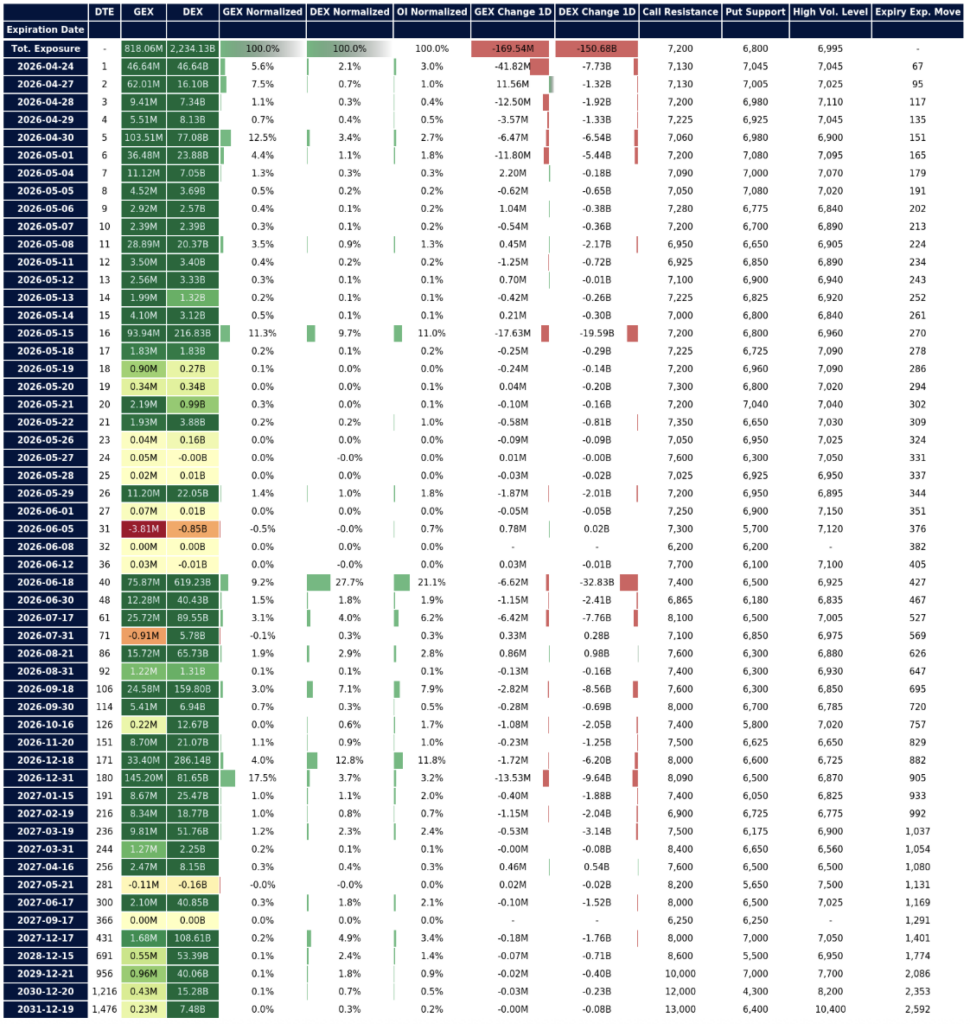
In the current snapshot, SPX options positioning reveals $818 million in net positive gamma exposure across all expirations. This is a meaningful figure because it establishes the broader environment: a positive gamma regime, where dealers are generally long gamma and hedging in ways that tend to stabilize price action.
However, looking at the total number alone is not enough. The real insight comes from breaking this exposure down across different expiration dates. Each expiration carries its own weight, its own positioning, and its own potential influence on price behavior. By analyzing how gamma is distributed across time, we can better understand where markets may experience stability, resistance, or shifts in dynamics.
The Nature of a Positive Gamma Environment
Before diving into the specific expirations, it’s important to understand what a positive gamma backdrop implies.
When dealers are long gamma, their hedging behavior typically works against large price swings. If the market rises, they may sell into strength; if it falls, they may buy into weakness. This creates a stabilizing effect, often leading to range-bound or “sticky” price action.
With $818M in net positive GEX, the baseline expectation is not chaos, but controlled movement. However, this stability is not uniform across all timeframes. It varies depending on where options positions are concentrated and that’s where the expiration breakdown becomes essential.
0DTE: Minimal Immediate Pressure
Starting with the shortest timeframe, the 0DTE (zero days to expiration) contracts for April 24 account for just 5.63% of total GEX, or approximately $46.6M.
This relatively small share suggests that same-day options are not exerting significant pressure on the market in this instance. While 0DTE trading has grown dramatically in recent years, its influence here appears limited compared to other expirations.
That said, key levels still emerge:
- Call wall at 7,130
- Put wall at 7,045
These levels form a tight range, indicating that intraday traders may expect price to oscillate within a narrow band. The implication is clear: limited volatility and no major directional moves expected purely from 0DTE flows.
In practical terms, this setup suggests a relatively quiet expiration, where price is more likely to remain contained than to break out aggressively.
Weekly Expiration: A Developing Pivot
Moving slightly further out, the weekly expiration on April 27 carries 7.49% of total GEX, or about $62M.
While still not dominant, this is a noticeable increase from 0DTE and becomes more important due to its timing just two business days away.
The put/call ratio of 1.18 indicates relatively balanced positioning, with a slight tilt toward puts. This balance suggests that neither bullish nor bearish forces are overwhelmingly dominant at this expiration.
What makes this level interesting is its role as a transition point. As 0DTE contracts expire, positioning tends to rotate into the next available timeframe. This means the weekly expiration can act as a secondary gamma pivot, where flows begin to shift and new dynamics take shape.
Rather than driving the market outright, this expiration helps bridge the gap between very short-term positioning and more significant structures further out.
Monthly Expiration: The Core Focus
The most important near-term expiration is clearly the monthly April 30 cycle, which holds 12.51% of total GEX ($103.5M).
This is the second-largest normalized gamma concentration outside of long-dated LEAPS, making it a central anchor for market structure.
Key levels here define a clear containment range:
- Call wall at 7,060
- Put wall at 6,980
This creates an 80-point range, effectively acting as a corridor where price may be guided or constrained.
What makes this expiration particularly noteworthy is the recent change in positioning. A one-day increase of +$20.35M in GEX suggests that dealers have actively repositioned, reinforcing these levels.
This repositioning strengthens the idea of “gamma magnets” price zones where hedging flows tend to pull the market.
- The 6,980 level acts as a potential floor if weakness emerges
- The 7,060 level serves as a cap on upside movement
As a result, this expiration is likely to play a major role in shaping price behavior in the coming days, especially as it approaches maturity.
May 15: The Next Major Node
Looking further ahead, the May 15 expiration carries 11.35% of total GEX ($93.9M).
This is another significant concentration, and its importance is amplified by a put/call ratio of 2.01, indicating a heavier skew toward puts.
Key levels for this expiration are:
- Put support at 6,800
- Call resistance at 7,200
This wider range reflects a broader market perspective, extending beyond the tighter constraints of the April expirations.
The May 15 cycle is also notable because it aligns with mid-month options activity, sometimes associated with larger institutional flows. As such, it is shaping up to be a future gamma concentration point, where positioning could influence market direction over a longer horizon.
Long-Dated LEAPS: The Structural Anchor
At the far end of the spectrum, the December 31 LEAPS stand out as a major outlier.
They account for 17.54% of total net GEX ($145.2M), making them the largest single concentration in the structure.
The put/call ratio of 0.07 is extremely skewed toward calls, suggesting a heavy concentration of long-dated call positions. These are often associated with portfolio hedging or long-term strategic positioning rather than short-term trading.
Because of their size and duration, LEAPS act as a structural anchor for the market. While they do not drive day-to-day price movements, they provide a long-term framework that influences how shorter-term positioning evolves around them.
Putting It All Together
When viewed as a whole, the distribution of gamma across expirations reveals a layered structure:
- Near-term (0DTE and weekly):
Light positioning, suggesting limited immediate volatility and tight ranges - Mid-term (April 30 and May 15):
Strong gamma concentrations, creating defined support and resistance zones - Long-term (LEAPS):
Large call-heavy positioning acting as a structural anchor
This multi-layered setup helps explain how markets can remain stable in the short term while still preparing for potential shifts as expirations approach.
One key concept that emerges is price stickiness. When gamma is concentrated at specific strikes, price often gravitates toward those levels and remains there until a catalyst such as expiration or new positioning forces a change.
As expirations pass, positioning resets, and the market may rotate toward new levels, creating a dynamic but structured environment.
Conclusion
The current SPX options landscape highlights the importance of understanding gamma not just as a single number, but as a distribution across time.
With $818M in net positive GEX, the overall environment favors stability. However, the real story lies in how this gamma is spread across expirations from low-impact 0DTE contracts to highly influential monthly and mid-term cycles, and finally to long-dated LEAPS that anchor the broader structure.
This layered positioning suggests a market that is contained in the near term, guided by clearly defined support and resistance zones, while also being shaped by larger forces that may come into play as time progresses.
Ultimately, gamma exposure provides insight into the mechanics of the market how and where dealers are likely to hedge, and how those hedging flows can influence price behavior. It does not predict direction, but it does offer a valuable framework for understanding why markets move the way they do.
Ask QUIN for more.