(function(){
var CN = 'menthorq_utm_params';
var LK = 'menthorq_utm_params';
var UK = ['utm_source','utm_medium','utm_campaign','utm_term','utm_content','utm_id'];
var CK = ['gclid','fbclid','msclkid','ttclid','twclid'];
var CD = 30;
var AK = UK.concat(CK);function sC(n,v,d){var e=new Date(Date.now()+d*864e5).toUTCString();var c=n+'='+encodeURIComponent(v)+';expires='+e+';path=/;SameSite=Lax';if(location.protocol==='https:')c+=';Secure';document.cookie=c;}
function gC(n){var m=document.cookie.match(new RegExp('(?:^|; )'+n+'=([^;]*)'));return m?decodeURIComponent(m[1]):'';}
function sv(d){var j=JSON.stringify(d);sC(CN,j,CD);try{localStorage.setItem(LK,j);}catch(e){}}
function hk(o){if(!o)return false;for(var i=0;i<AK.length;i++)if(o[AK[i]])return true;return false;}
function nm(d){if(!d)return null;if(d.first)return d;if(hk(d))return{first:d,last:d};return null;}
function ld(){var r=gC(CN);if(r){try{var n=nm(JSON.parse(r));if(n)return n;}catch(e){}}try{var s=localStorage.getItem(LK);if(s){var n=nm(JSON.parse(s));if(n)return n;}}catch(e){}return null;}
function mg(p,n){var o={};if(p)for(var k in p)o[k]=p[k];for(var k in n)o[k]=n[k];return o;}var ps = new URLSearchParams(window.location.search);
var fd = {}, has = false;
for (var i = 0; i < AK.length; i++) {
var v = ps.get(AK[i]);
if (v) { fd[AK[i]] = v; has = true; }
}// Click-ID synthesis: when only a click-id is present (no utm_source), derive
// utm_source/utm_medium so downstream analytics groups under the right channel.
var SY = {
gclid: ['google', 'cpc'],
fbclid: ['facebook', 'cpc'],
msclkid: ['bing', 'cpc'],
ttclid: ['tiktok', 'cpc'],
twclid: ['twitter', 'cpc']
};
if (has && !fd.utm_source) {
for (var sk in SY) {
if (fd[sk]) { fd.utm_source = SY[sk][0]; fd.utm_medium = SY[sk][1]; break; }
}
}if (has) {
fd.captured_at = new Date().toISOString();
var ex = ld();
// Last-touch: merge new fields ON TOP of previous last (preserva campi pregressi)
var newLast = ex && ex.last ? mg(ex.last, fd) : fd;
// First-touch: se ex.first ha almeno un UTM, e' completo e sticky.
// Se ex.first esiste ma e' click-id-only (orphan), completa con i campi nuovi.
// Se ex.first non esiste, usa fd come first.
var newFirst;
if (ex && ex.first) {
var firstHasUtm = false;
for (var i = 0; i < UK.length; i++) if (ex.first[UK[i]]) { firstHasUtm = true; break; }
newFirst = firstHasUtm ? ex.first : mg(ex.first, fd);
} else {
newFirst = fd;
}
sv({first: newFirst, last: newLast});
return;
}var raw = gC(CN);
if (raw) {
try {
var p = JSON.parse(raw);
if (!p.first && hk(p)) sv({first: p, last: p});
} catch(e) {}
return;
}try {
var s = localStorage.getItem(LK);
if (s) { var n = nm(JSON.parse(s)); if (n) sv(n); }
} catch(e) {}
})();
var breeze_prefetch = {"local_url":"https://menthorq.com","ignore_remote_prefetch":"1","ignore_list":["/account/","/login/","/thank-you/","/wp-json/openid-connect/userinfo","wp-admin","wp-login.php"]};
//# sourceURL=breeze-prefetch-js-extra
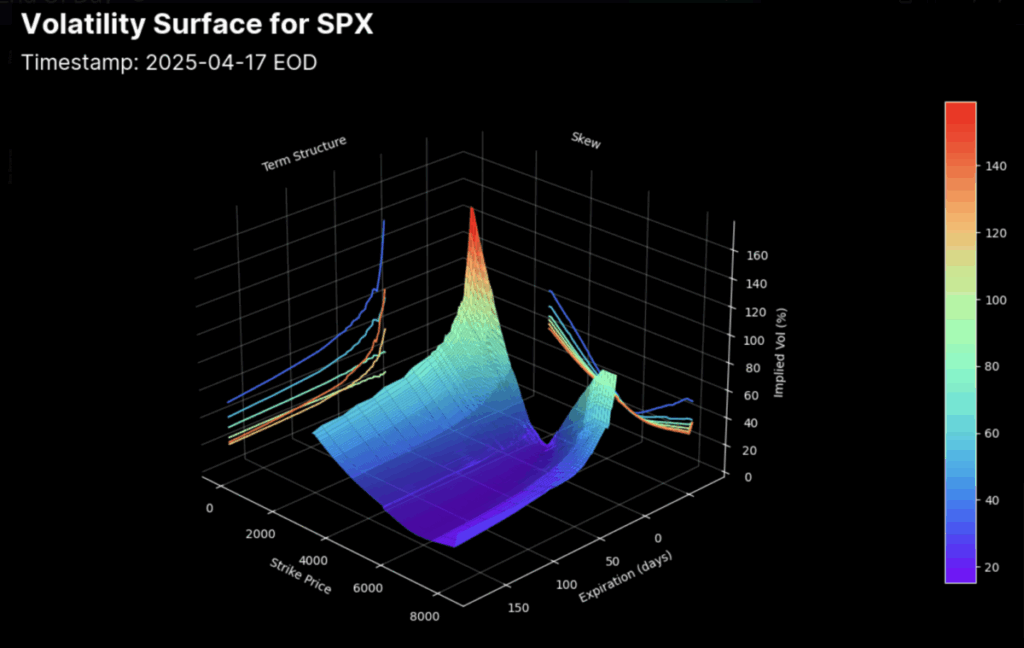
3D Volatility Surface: See the Full Picture of Market Risk
The Volatility Surface is a three-dimensional representation of implied volatility (IV) plotted against both strike prices and expiration dates. Unlike the traditional volatility smile, which only shows how IV varies across strikes at a single expiry, the surface gives you the full picture — a landscape of how volatility is priced across the entire options chain.
When visualized, the surface looks like a 3D grid or wave. The X-axis represents the strike price, the Y-axis shows implied volatility, and the Z-axis (depth) reflects the time to expiration. This creates a powerful, multi-layered view of market expectations and risk pricing.
3D Volatility Surface 8
While a traditional 2D volatility smile helps identify sentiment at one point in time, it lacks the ability to show how the market’s pricing of risk evolves across different expiries. That’s where the Volatility Surface stands out.
It allows traders to:
Identify term structure skews (e.g., elevated short-term IV vs. longer-term calm)
Spot event-driven volatility clusters like earnings or macro announcements
Understand how risk is priced over time and across price levels
These insights are critical when building multi-leg or time-based strategies, such as spreads, calendars, and diagonals — or when selling volatility into events.
Using the Volatility Surface in Trading
Let’s look at how this data becomes actionable:
🔹 Options Traders
You notice a steep upward curve on the front-month OTM puts for TSLA, indicating elevated short-term fear. This could be the market pricing in near-term uncertainty — a perfect setup for premium sellers or traders looking to structure short-dated credit spreads at high IV.
🔹 Futures Traders
Analyzing the surface for SPX or QQQ might reveal a flattening term structure, suggesting that implied risk is tapering off. This aligns well with strategies where you reduce size or lean into mean reversion setups — supported by lower expected volatility ahead.
🔹 Swing Traders
You spot IV spikes in 3–4 week expiries, especially on strikes around key support zones. This could hint at institutional hedging, helping you time your swing entries more accurately.
Volatility Surface 2D
This chart offers a flattened, heatmap view of the 3D Volatility Surface, allowing you to quickly scan implied volatility (IV) levels across both strike prices (Y-axis) and expiration dates (X-axis).
How to Read It:
Y-Axis (Vertical): Strike Prices — from low to high
X-Axis (Horizontal): Days to Expiration — from short-term (3 days) to long-term (171 days)
Cell Values (%): Implied Volatility at that specific strike and expiration
Color Gradient: Indicates IV intensity
3D Volatility Surface 9
Join us today
Access daily Market Research and our interactive Dashboard. Make better trading decisions.